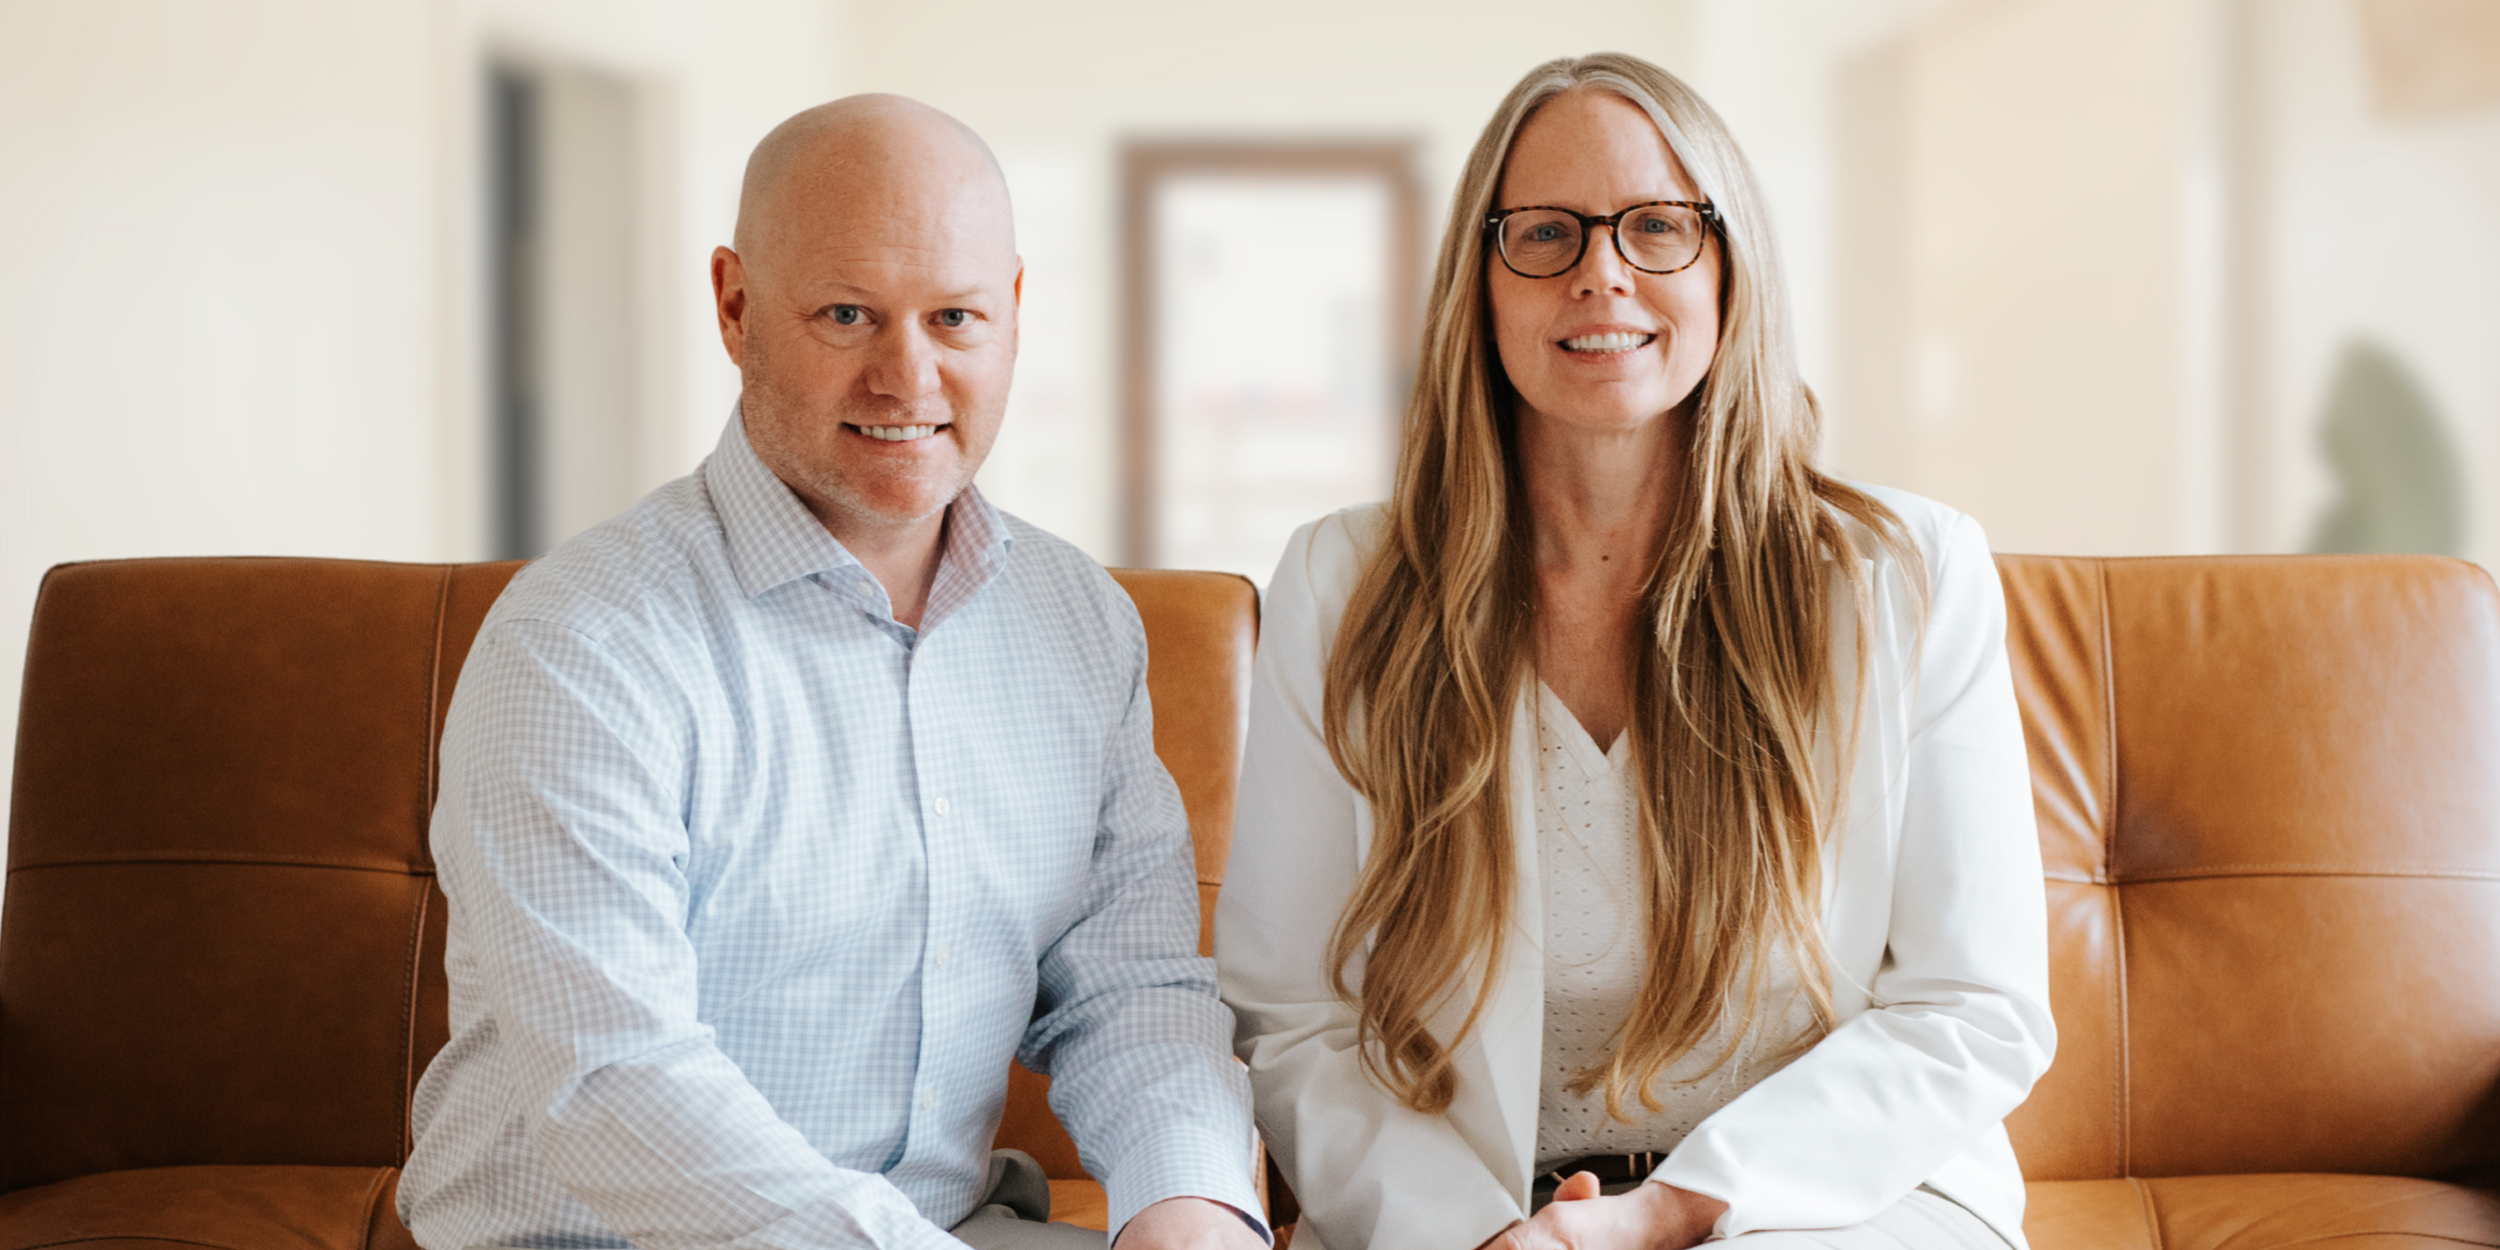
Your Northern Michigan Mortgage Team
Loan officers, a loan officer assistant, and a processor who all live and work up here. When you call, you get someone who knows the difference between a Manton septic inspection and a Traverse City condo association. That matters more than people think.
The Kirby and Angie Team is a Union Home Mortgage branch with offices in Traverse City and Manton, Michigan. Our loan officers, loan officer assistant, and processor are all local, and we serve buyers and homeowners across Northern Michigan with conventional, FHA, VA, USDA, construction, manufactured home, and non-QM loan options, subject to credit approval.
The people who actually answer the phone
Every loan officer here originates every day. Nobody is handing you off to a call center in another state.
Angie Anderson
Team Loan OfficerAngie takes pride in making the mortgage experience straightforward and comfortable. Her thoughtful approach, attention to detail, and strong communication help borrowers understand their options and successfully navigate every stage of their home financing journey.
Kirby Slocum
Team Loan OfficerKirby has decades of experience in financing. He is committed to building lasting relationships and helping clients make confident financial decisions through honest guidance, personalized mortgage strategies, and dependable support from the first conversation through closing and beyond.
Your market could be next
We are adding licensed loan officers in Northern Michigan markets where we do not have an originator yet. You keep your own brand. We bring the ops team.
Join Our TeamThe reason files actually close on time
Our loan officer assistant and processor are on our team and local to Northern Michigan. They are the ones chasing the documents, the title work, and the appraisal so you are not left guessing where your loan stands.
Jill Bredahl
Team Loan Officer AssistantJill Bredahl brings a strong background in banking, finance, and customer service to the Kirby & Angie Loan Team. Beginning with the first phone call, Jill provides responsive, personalized support while helping clients stay informed and organized throughout the mortgage process.
Beth Dellar
Team Loan ProcessorBeth brings valuable experience in banking, title, and years of mortgage processing to the Kirby & Angie Loan Team. Her well-rounded industry background allows her to anticipate challenges, manage details, and guide each loan smoothly from contract through closing.
Email the team, not one person
Send loan emails to your loan officer's team inbox and the entire team gets them. Nothing sits in one inbox while someone is at a closing.
Who handles what, in order
-
1
Loan OfficerConsultation through disclosures
Starts with your mortgage consultation, in person, by phone, or on Zoom. Your loan officer reviews your goals, credit, and options and completes the application with you, collects your employment and income documents, completes your pre-approval, and issues your pre-approval letter.
If pre-approval is not an option yet, your loan officer will lay out a plan to get you on the right track.
Once you are under contract, your loan officer updates your file with the contract details, makes sure everything works, and sends your initial disclosures for e-signature. After you e-sign, your file goes back to the loan officer assistant.
-
2
Loan Officer AssistantPre-approval and contract
During pre-approval, completes verification of employment if applicable and submits your file for any pre-underwriting.
Once you are under contract, updates your file with all contacts and orders title work and the appraisal.
-
3
Loan ProcessorUnder contract or refinance locked
Steps in after you are under contract, or once your refinance is locked. Coordinates with title, submits your file to underwriting for conditional approval, then collects any documents underwriting requires to clear your file for closing.
-
4
UnderwritingConditional to final approval
Receives your file from the processor, underwrites it, and issues conditions for anything required to get your file to closing. Underwriting then issues final approval and hands your file back to the team and the processor to get you clear to close.
-
5
Closing and Post-ClosingClosing day and for life
You will either sign all documents at closing, e-sign some ahead and sign the rest at closing (a hybrid closing), or e-sign everything through RON (remote online notary).
Once you are closed and your loan is disbursed, congratulations are in order. Your loan officer and our team stay in contact with you as your mortgage advisor team for life, and we constantly monitor your loan to make sure you are in the best possible position.
When you work with us, you are part of our mortgage family
We like to thank our current and past clients for referring their friends and family, and we take those referrals very seriously.
After closing, you will get a thank-you card from us with three referral cards tucked inside. Your name and your agent's name are already on them, so we know who to thank. Give one to a friend, a coworker, or that brother-in-law who keeps talking about buying.
Just good people helping good people.
What not to do while you get pre-approved, go under contract, or get ready to refinance
Make every payment on time
If you are more than 30 days late on a revolving or installment loan, that will complicate your approval.
Don't take out new credit
If you are trying to build credit in order to buy a home, contact our team for your free mortgage consultation. Let's come up with your plan together.
Keep your money in the bank
Stashing cash at home to buy a home can lead to seasoning issues. Your cash needs to be in the bank for a minimum of 60 days before you use it to purchase a home. Getting a gift from family? There is a procedure for documenting that as well. Always consult with your loan officer.
Know if your income is variable
If you average less than 40 hours per week, you are likely considered variable income. That means the last 2 years of your income have to be averaged.
Keep 12 months of the same pay type
You need 12 months of the same pay type in the same industry or job title. For example:
- Salary to hourly in a new job: you will need a 12 month history.
- W-2 employee to self-employed: you will need 2 full years of tax returns.
- Hourly truck driver to paid by the mile: you will need 12 full months by the mile.
- Employed through a temp agency: you will need to be hired in full time before approval.
Have questions about your employment, income, or future job prospects? Contact us.
Already under contract?
Do not apply for new credit, make large purchases, change jobs, or make large cash deposits. Pay all of your liabilities on time, including rent and land contract payments.
Where to find us
Traverse City
1396 Douglas Dr, Ste 22ATraverse City, MI 49696
Manton
113 W Main StManton, MI 49663
- Traverse City
- Cadillac
- Manton
- Lake City
- Petoskey
- Charlevoix
- Gaylord
- Grayling
- Houghton Lake
- Manistee
- Frankfort
- Elk Rapids
- Boyne City
- The U.P.
What you get by working with a team up here
Local judgment
Wells, septic, seasonal income, land, and manufactured homes on owned land are normal up here. We structure for them from the start.
Loan contacts for life
Union Home Mortgage keeps servicing on the large majority of the loans it originates, so the team that closed your loan is typically still your team later.
Lifetime loan monitoring
We keep watching your loan after closing and reach out when a refinance or restructure may make sense. No chasing required.
Questions people ask about our branch
Where is the Kirby and Angie Team located?
We have two offices: 1396 Douglas Dr, Ste 22A in Traverse City, and 113 W Main St in Manton. We work with clients across Northern Michigan, including markets without a physical office.
Who will I work with on my loan?
Your loan officer leads the loan from consultation through disclosures. Our loan officer assistant handles verification of employment, title work, and the appraisal order. Our processor coordinates with title and underwriting to get your file clear to close.
Who should I email about my loan?
Use your loan officer's team inbox: teamangie@uhm.com if your loan is with Angie, teamkirby@uhm.com if it is with Kirby. The entire team gets those emails, so your question does not wait on one person.
Can I use cash I have been saving at home to buy a house?
Cash kept at home can lead to seasoning issues. Your cash needs to be in the bank for a minimum of 60 days before you use it to purchase a home. If you are getting a gift from family, there is a procedure for documenting that as well. Talk to your loan officer before you move any money.
I changed jobs recently. Can I still get approved?
You need 12 months of the same pay type in the same industry or job title. Going from salary to hourly requires a 12 month history, going from W-2 to self-employed requires 2 full years of tax returns, and temp agency employees need to be hired in full time before approval. Contact us with your specific situation.
What should I avoid once I am under contract?
Do not apply for new credit, make large purchases, change jobs, or make large cash deposits. Pay all of your liabilities on time, including rent and land contract payments.
How does closing work?
You will either sign all documents at closing, e-sign some ahead and sign the rest at closing (a hybrid closing), or e-sign everything through RON (remote online notary). After closing, your loan officer and our team stay in contact as your mortgage advisors and keep monitoring your loan.
Do you only lend in Traverse City?
No. We serve all of Michigan with a focus on Northern Michigan, including Cadillac, Gaylord, Petoskey, Manistee, Grayling, and the U.P.
Will my loan be sold after closing?
Union Home Mortgage retains servicing on most loans it originates, but servicing can vary by loan program. Ask your loan officer what applies to your loan.
Are you hiring loan officers?
Yes. We are adding licensed, actively originating loan officers in Northern Michigan markets where we do not have one yet. See our Join Our Team page.
Talk to someone who lives here
Fifteen minutes, no pressure, and a straight answer on what you may qualify for. Kirby 231-709-3136 · Angie 616-581-6123 · KirbyandAngie@uhm.com